
Mumbai: Keeping your salary, shopping money and savings in one bank account can make the balance misleading. Money that appears spare may already be needed for rent or loan repayments.
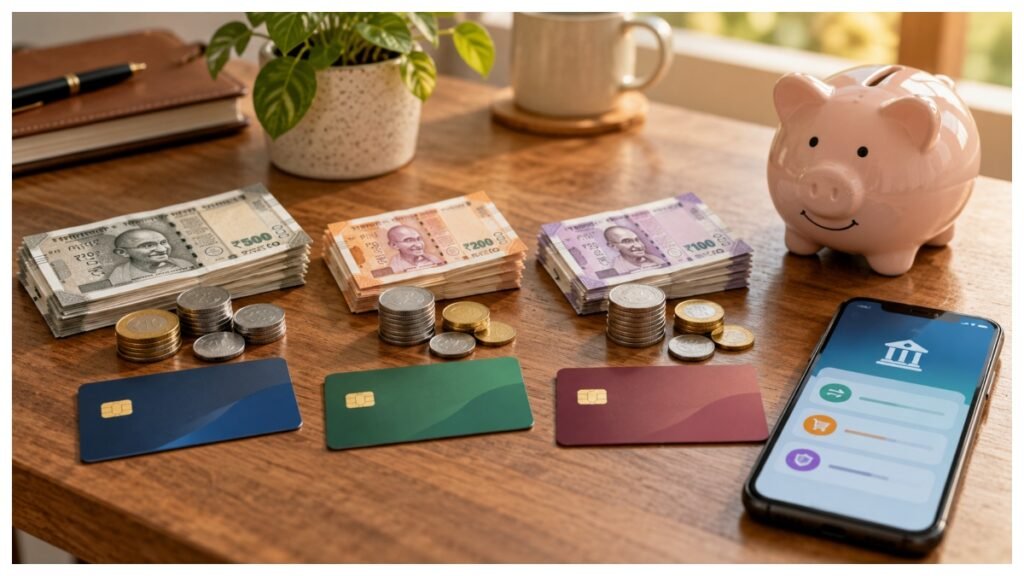
An ABP Live report outlines an approach: give separate accounts separate jobs, so essential payments, optional spending and emergency savings remain easier to track.
Three Accounts, Clear Roles
The salary account can handle income and regular commitments such as rent, monthly loan instalments, electricity and water bills.
A second account can hold a fixed monthly allowance for shopping, entertainment and eating out. Its balance shows how much remains within that spending budget.
The third account is for emergencies. Keeping this reserve away from everyday transactions helps protect money meant for unexpected needs.
How Much Is Enough?
The report suggests a reserve covering three to six months of essential expenses. People with uncertain earnings, greater family responsibilities or higher debt commitments may need more.
For illustration, essential monthly expenses of Rs 30,000 would mean a target of Rs 90,000 to Rs 1.8 lakh. The calculation uses necessary spending, rather than total salary.
Build The Habit Gradually
The US Consumer Financial Protection Bureau says even small savings can offer protection. Its guidance recommends setting a goal, contributing consistently and checking progress regularly.
Also read: RBI Tightens Loan Recovery Rules, Banks Cannot Threaten Borrowers Or Lock Phones Freely
Automatic transfers can make contributions easier to maintain. However, account holders should check their balance before scheduled transfers and adjust the amount when income changes.
Money received occasionally, including cash gifts, can also help build the reserve. Saving part of such receipts can support people whose regular earnings leave little room for savings.
Know When To Use It
The bureau advises defining what counts as an emergency. Unexpected repairs, medical bills or lost income can justify using the fund.
A reserve can reduce dependence on borrowing, where interest and fees increase the eventual cost. After withdrawing money for a genuine need, rebuild the balance gradually and keep the fund safe and accessible.